When a bill lands days before payday, early-paycheck apps — also called earned wage access apps — let you tap money you have already earned instead of waiting for payday. The apps below are legit, widely used options in the US, but they are not free money: limits, fees, and tip models vary, so compare carefully before you advance. Used occasionally for real emergencies, they beat overdraft fees and payday loans; used every week, they can quietly shrink your next paycheck.
1. EarnIn — Access Pay You Have Already Earned
EarnIn lets you access up to $150 a day and up to $750 per pay period from wages you have already earned, with no mandatory fees or interest — the app runs on optional tips. Connect your bank account and payroll, verify your work schedule, and advances typically arrive within one to two business days, or faster with the Lightning Speed option.
EarnIn also offers a free checking account and a Cash Out feature that tracks your earnings automatically. Tip only what you can afford: the advance comes straight out of your next paycheck, so keep advances small and occasional.
Link your bank account early and verify your employment details before you need money — setup takes a day or two, and it is too late to rush when a bill is due.
2. Dave — ExtraCash Advances With No Credit Check
Dave’s ExtraCash feature offers advances up to $500 with no credit check and no interest. There is a small monthly membership fee for Dave’s banking features, and express transfers to your debit card cost an extra fee — standard transfers are slower but cheaper.
Dave also helps you find side gigs and track upcoming bills, which makes it useful beyond the advance itself. Set the repayment date to your actual payday and avoid stacking advances from multiple apps at once.
Use standard delivery whenever possible; express fees add up fast if you advance every pay period.
3. Brigit — Cash Advances Plus Budgeting Tools
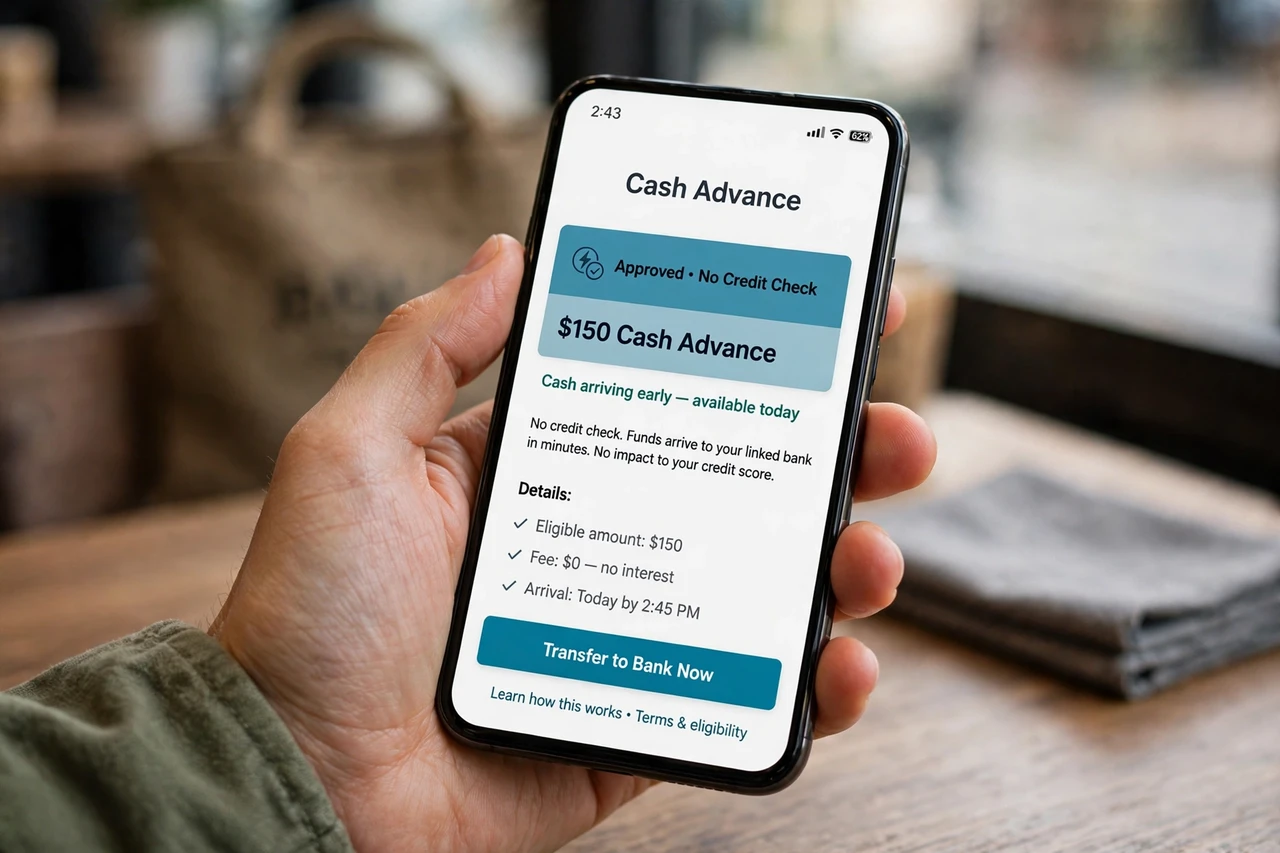
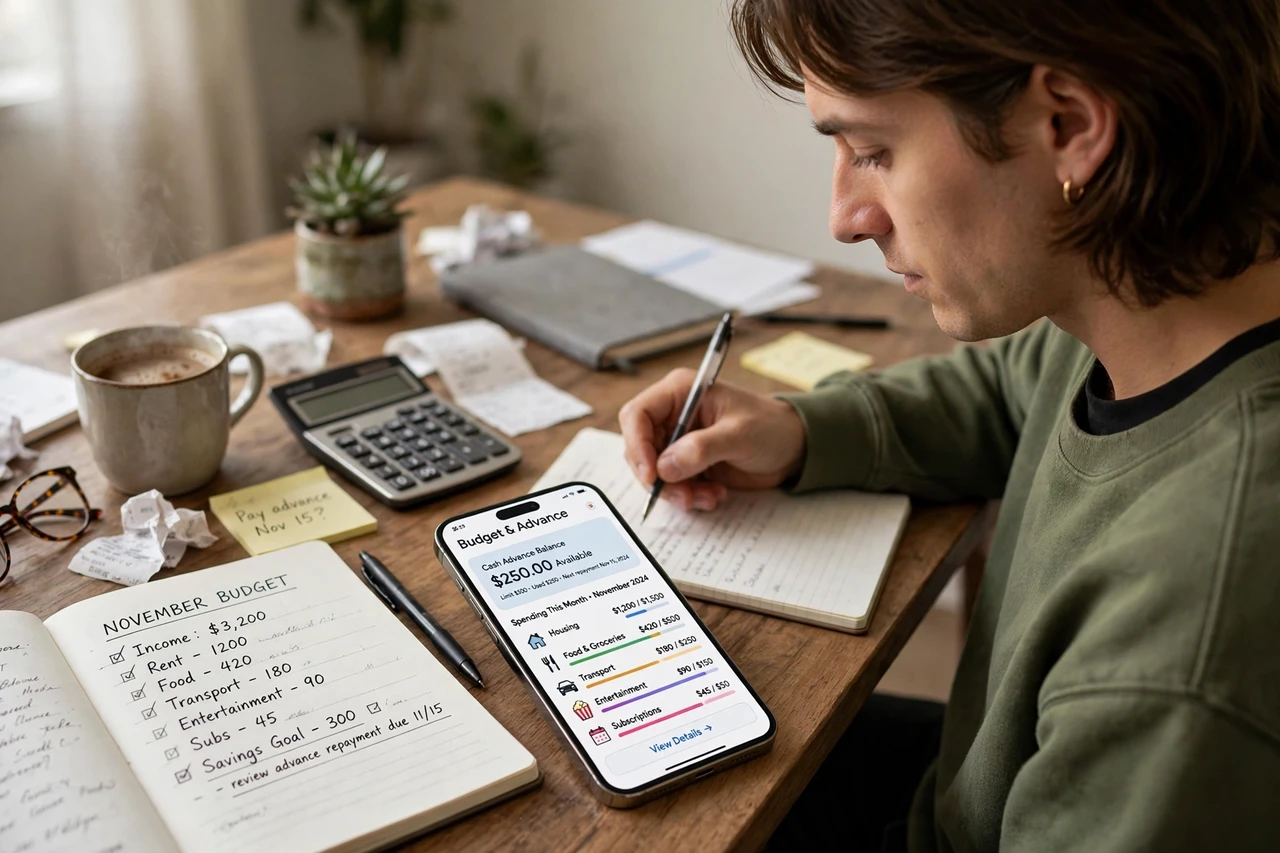
Brigit offers instant cash advances up to $250 for eligible users, with no interest and no credit check. The app analyzes your income and spending to predict shortfalls before they happen, and its budgeting tools help you avoid needing the next advance.
Brigit’s Plus plan carries a monthly fee, so weigh it against how often you actually need advances. If you only need one advance a year, a no-subscription option may be cheaper.
Turn on the app’s shortfall alerts so you see a gap coming days early instead of discovering it on bill day.
4. MoneyLion — Instacash With No Fees or Interest
MoneyLion’s Instacash offers advances up to $500 with no interest, no credit check, and no mandatory fees for standard delivery. The app connects to your bank account, verifies your direct deposits, and increases your limit over time as your history builds.
MoneyLion also bundles banking, investing, and credit-building tools, which makes it a reasonable all-in-one choice if you want more than just advances. Express delivery costs extra, so plan ahead when you can.
Your limit grows with direct deposit history, so route your paycheck through the account for a few cycles before judging the limit.
5. Chime SpotMe — Fee-Free Overdraft Up to $200
Chime’s SpotMe is not a traditional advance — it lets eligible checking account holders overdraw up to $200 on debit purchases with no overdraft fees. You need qualifying direct deposits to unlock it, and the limit grows with account history.
SpotMe covers debit card purchases and cash withdrawals, and your next deposit simply brings the balance back to zero. It is one of the cheapest options on this list because there are no fees at all — but it only works if you bank with Chime.
SpotMe requires qualifying direct deposits, so set up direct deposit first and check your eligibility in the app before relying on it.
6. Current — Paycheck Advance Up to $500
Current’s Paycheck Advance offers up to $500 for eligible members with qualifying direct deposits, with no credit check and no mandatory fees. The mobile bank also offers early direct deposit, getting your paycheck up to two days early — which alone can solve many timing problems.
Current’s advance eligibility depends on your direct deposit history, so new accounts start lower. Pair the advance with the early paycheck feature and you may rarely need to borrow at all.
Early direct deposit alone can fix many timing problems — check whether your paycheck already arrives early before advancing.
7. Varo Advance — Small Advances With One Flat Fee
Varo Advance offers up to $250 for eligible bank account holders, with a single flat fee per advance and no interest or tips. Qualification depends on direct deposit activity, and the fee is disclosed upfront before you accept.
Because the fee is flat rather than percentage-based, small advances cost the same as larger ones — so only advance what you truly need. Varo’s banking app also includes automatic savings tools that help break the paycheck-to-paycheck cycle.
Since the fee is flat, avoid tiny advances that make the fee a large percentage of what you borrow.
8. Albert — Cash Advances Plus Smart Money Tools
Albert offers cash advances up to $250 with no interest, no credit check, and no late fees, alongside budgeting and automatic savings features. The app reviews your income and bills to suggest advances only when you genuinely need one.
Albert’s optional Genius subscription adds human financial advice, but the advance feature itself does not require it. Standard delivery takes a few days, so request early when a bill is coming.
Use the budgeting alerts alongside advances — the goal is fewer advances over time, not larger ones.
9. Klover — Advances for Everyday Expenses
Klover offers advances up to $200 based on your bank activity and employment, with no interest and no credit check. The app also rewards you with points for everyday activities like scanning receipts, which can unlock higher limits over time.
Klover’s model suits people who need small, occasional advances rather than large ones. Keep the advance modest and repay on payday to keep your limit growing.
Scan receipts and complete the app’s activities to raise your limit gradually rather than expecting the maximum immediately.
10. Empower — Cash Advances Up to $400
Empower offers cash advances up to $400 for eligible users with no interest, no credit checks, and no late fees. The app connects to your checking account, monitors your balance, and can send advances automatically when it predicts a shortfall.
Empower also includes budgeting and automatic savings, making it a solid choice if you want advances plus a plan to need them less often. As with every app here, borrow only what your next paycheck can comfortably repay.
Turn on automatic shortfall detection so advances arrive before a bill bounces, not after.
How to Choose the Right Early-Paycheck App
Start with the bank you already use: if your bank offers an advance or overdraft feature like SpotMe, it will usually be the cheapest option because there is nothing new to sign up for. If it does not, compare the remaining apps on total cost, not headline limits — a $500 limit with a monthly subscription and express fees can cost more than a $250 limit with a single flat fee.
Check three things before accepting any advance: the total cost including tips and express fees, the exact repayment date, and whether the app requires a subscription you will forget to cancel. Request the advance at least two days before the bill is due if you are using standard delivery, and always borrow less than the maximum — your next paycheck still has to cover rent, food, and gas.
Mistakes to Avoid With Paycheck Advances
The most expensive mistake is stacking advances from two or three apps at once: each one deducts from the same paycheck, leaving you short again next week and tempted to borrow again. Another is tipping generously on every advance out of habit — tips are optional, and on a $100 advance a large tip is effectively a high interest rate.
Avoid using advances for non-essentials like shopping or dining out; the math only works for genuine timing emergencies like rent, utilities, or medicine. Finally, treat repeated advances as a warning sign, not a routine: if you need one every pay period, the fix is a budget change or extra income, not a bigger advance limit.
Frequently Asked Questions
Are early-paycheck apps legit?
Yes — the early-paycheck apps on this list are legitimate, widely used US financial apps. They are not scams, but they are also not free: check each app’s fees, tips, and subscription costs before advancing, since costs vary widely.
Do early-paycheck apps check your credit?
Most earned wage access apps do not run a credit check. Instead, they verify your income, employment, and bank activity to set your advance limit. A low credit score generally does not block you.
How fast do you get money from an early-paycheck app?
Standard transfers typically take one to three business days, while express transfers to a debit card can arrive within minutes for an extra fee. If you need money today, choose an app with instant delivery and confirm the fee first.
Is it better to use an early-paycheck app or a payday loan?
Early-paycheck apps are almost always cheaper than payday loans, which charge triple-digit interest rates. But both shrink your next paycheck — so use advances only for genuine emergencies, and build a small emergency fund to reduce future borrowing.
Conclusion
Early-paycheck apps solve a timing problem, not an income problem. Pick the app with the lowest total cost for your situation, advance only what you need, and let your next paycheck arrive whole. If timing is your main issue, also check out these apps that pay weekly for faster regular income.