Quarterly dividends and annual payouts test your patience — monthly income pays the bills. These 5 passive income ideas that pay monthly deliver cash on a regular monthly schedule, so you can plan, budget, and watch the deposits stack up twelve times a year.
1. Monthly-Paying Dividend ETFs and REITs
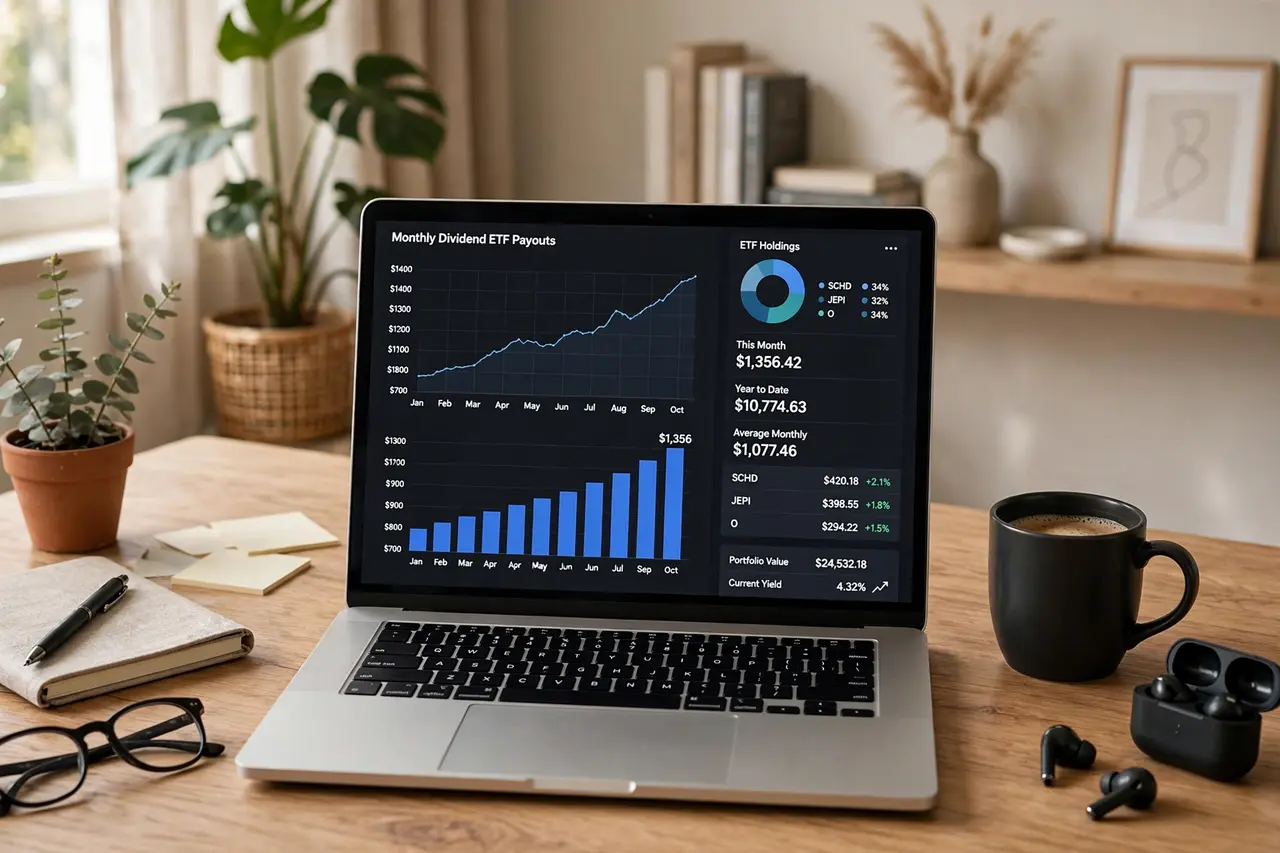
Most dividends arrive quarterly, but a select group of ETFs and REITs pay every single month — funds like monthly dividend ETFs distribute income from dozens of holdings in one predictable payment. A $10,000 position yielding 6% annually puts roughly $50 in your account each month, automatically reinvested or paid as cash. It’s the closest thing to a paycheck that investing offers.
Focus on funds with long histories of uninterrupted monthly payments rather than chasing the highest yield, which often signals risk. Hold them in a Roth IRA and those monthly payouts compound tax-free for decades.
2. Treasury Bill and Bond Interest Payments
U.S. Treasury bills and high-quality bonds pay interest like clockwork — T-bills can be laddered so something matures every month, creating a steady drip of interest income. With yields around 4% to 5%, a $20,000 T-bill ladder generates roughly $70 to $85 monthly, backed by the U.S. government. It’s boring, safe, and beautifully predictable.
Buy T-bills directly through TreasuryDirect with no fees, and set maturities 4, 8, 13, 17, and 26 weeks out so cash frees up continuously. Reinvest automatically and your monthly income grows without a single decision.

3. Covered-Call ETFs for Monthly Distributions
Covered-call ETFs sell options against their stock holdings and pass the premium income to you as monthly distributions — yields often reach 7% to 12% annually, far above regular dividends. A $10,000 investment at a 9% distribution rate pays about $75 every month. The tradeoff is capped upside in raging bull markets, which many income investors gladly accept.
These suit taxable accounts less (distributions are often taxed as ordinary income), so consider holding them in tax-advantaged accounts. Start with established covered-call ETFs with multi-year track records, not brand-new funds chasing headline yields.

4. Display Ad Revenue From a Niche Website
A content website earning through display ad networks like Mediavine or Raptive pays out monthly once you cross their traffic thresholds — typically $15 to $30 per 1,000 visitors. A modest site with 50,000 monthly visitors can generate $750 to $1,500 every month, deposited like clockwork. Unlike affiliate income that fluctuates with buyer behavior, ad revenue simply tracks your traffic.
Pick an evergreen niche (personal finance, home improvement, food) and publish 2 to 3 helpful articles weekly for a year. Traffic compounds slowly, then suddenly — most sites see the monthly payout curve bend upward around month 9 to 12.
5. In-App Advertising From a Free Mobile App
A simple free mobile app — a habit tracker, a white-noise generator, a unit converter — earns monthly ad revenue every time users open it. Ad networks pay per thousand impressions, and even a modest app with 10,000 active users can generate $200 to $800 a month. No-code app builders mean you can launch without programming skills.
Success comes from solving one tiny problem extremely well and getting featured in app-store search. Update the app quarterly to keep ratings high; a 4.5-star average is the difference between steady downloads and obscurity.

Frequently Asked Questions
Which monthly passive income idea is best for beginners?
Treasury bills are the safest starting point — no market risk and true monthly cash flow. Monthly dividend ETFs come next for slightly higher yields with modest risk. Content websites and apps pay more long-term but need months of upfront work.
How much money do I need to earn $500 a month passively?
At a 6% yield, about $100,000 in monthly-paying investments generates $500 a month. Content-based options (websites, apps) need time instead of capital — typically 6 to 12 months of consistent effort before reaching $500 monthly.
Are monthly payouts better than quarterly dividends?
For budgeting and compounding, yes — monthly payments let you reinvest faster and smooth out cash flow. The underlying returns matter more than frequency, but all else equal, monthly beats quarterly.
Do I pay taxes on monthly passive income?
Yes — interest, dividends, and distributions are taxable in the year received. Holding income investments in a Roth IRA or 401(k) shields the monthly payouts from annual taxes; in taxable accounts, set aside 15% to 25% for the IRS.
Conclusion
Monthly payouts turn passive income from a vague promise into a visible habit — twelve deposits a year you can watch, measure, and grow. Start with the safest option that fits your capital, automate the reinvestment, and let the calendar do the compounding.