Learning how to reinvest dividends is one of the simplest ways to help a long-term income portfolio grow, because each payout can buy more shares that may pay dividends of their own in the future. That compounding effect only works when you have a clear plan, though. Without one, small payouts can sit idle as cash, pile up in a single holding, or land in the wrong type of account for your tax situation. This guide focuses on reinvestment strategies rather than picking individual stocks or funds. If you are still choosing income holdings, start with our dividend investing tips for passive income, then use the ideas below to put every payout to work deliberately. Remember, this is general education only, not personal financial advice, and future returns are never assured.
1. Switch On Full Automatic Reinvestment for Your Core Holdings
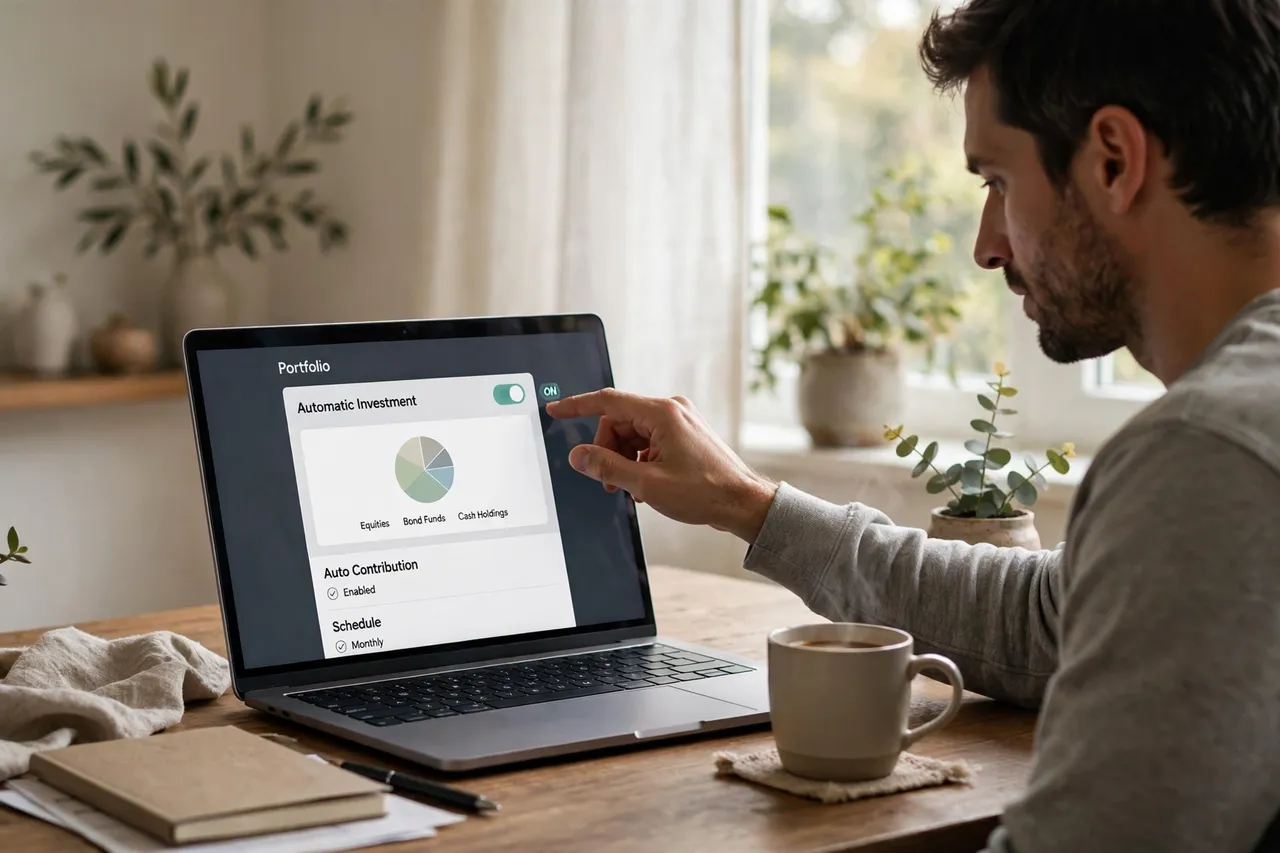
Automatic reinvestment removes the most common reason dividends go unused: forgetfulness. When the setting is on, each payout is used to buy additional shares of the same holding, usually in small fractional amounts, without you having to place an order or remember a date. That consistency matters more than timing, because it keeps your money working through quiet months when you might otherwise leave cash sitting in your account.
Check that the setting is actually active for each holding you intend to reinvest, since some brokerages set it per position rather than per account. Also confirm whether fractional shares are supported, because a small payout cannot always buy a whole share. A quick settings review once after opening an account can prevent months of idle payouts.
2. Split Each Dividend Payout Between Reinvestment and Cash Reserves
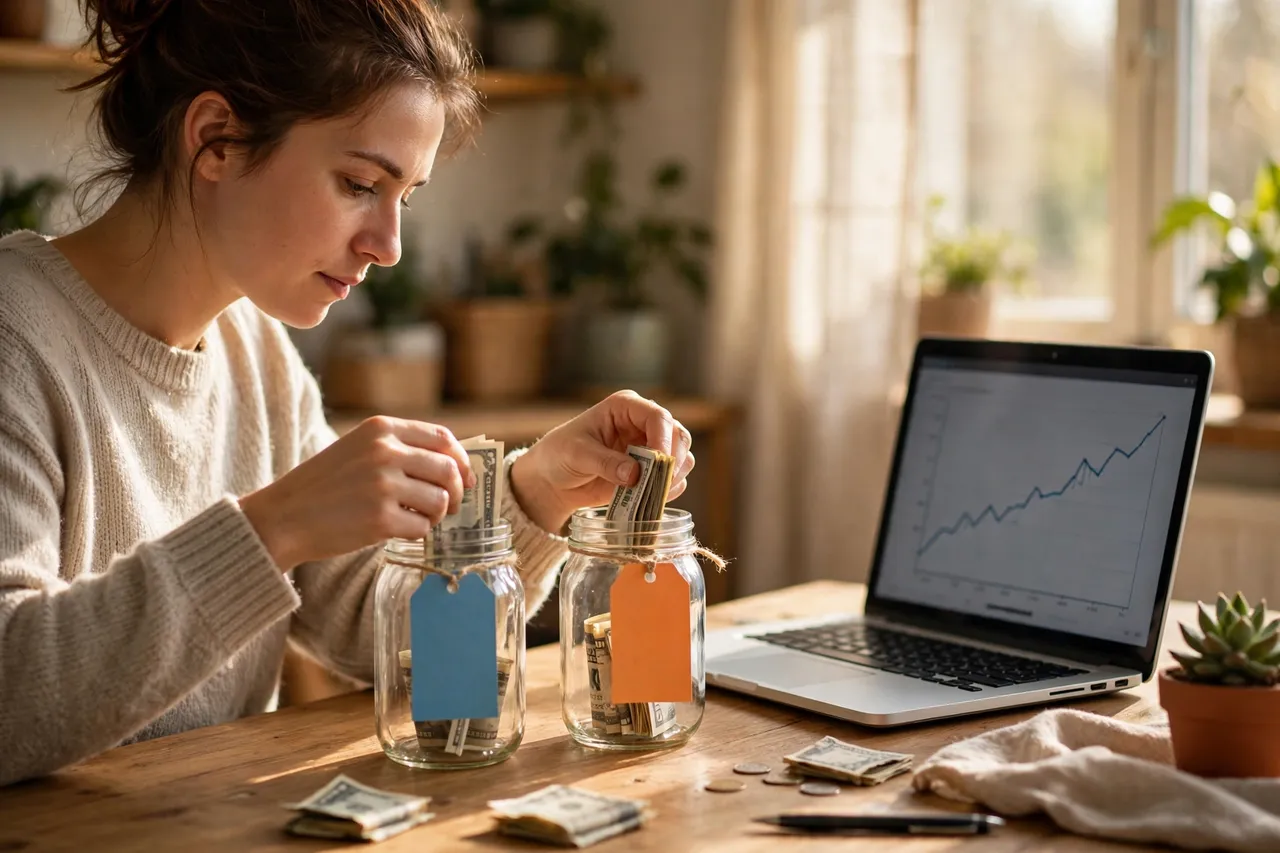
Full reinvestment is not the only sensible choice. Some investors reinvest part of each payout and keep the rest as cash, which can be useful if you are building an emergency reserve, saving for a near-term goal, or simply want flexibility. A partial approach still lets compounding do much of its work while giving you a growing cash cushion you control.
Decide the split in advance, for example by reinvesting most of each payout and holding back a smaller share, rather than choosing fresh each time a payment arrives. Write the rule down and revisit it only when your goals change. That way, a single large payout will not tempt you into an unplanned purchase.
3. Rebalance by Pointing New Dividends at Underweight Holdings
Instead of automatically buying more of whatever just paid you, you can direct dividend cash toward holdings that have drifted below your target mix. This is a gentle form of rebalancing: it nudges your portfolio back toward balance without selling anything or triggering a taxable sale in a taxable account. Over time, it can keep one strong holding from quietly taking over your whole portfolio.
This approach takes a little more attention, since you need to know your target mix and check it from time to time. A simple spreadsheet with your intended percentages is enough. When a payout arrives, compare your current mix, send the cash to the most underweight holding, and move on. The habit matters more than perfect precision.
For more ideas, see passive income ideas that actually work.
4. Place Reinvested Dividends in Tax-Advantaged Accounts First
Where you reinvest can matter as much as how much you reinvest. In a retirement account such as a traditional or Roth IRA, reinvested dividends generally grow without creating a yearly tax bill on those payouts, while payouts in a taxable brokerage account may be taxable in the year you receive them, even when reinvested. That difference is worth understanding before you choose where to hold income-producing investments.
This is not a reason to avoid taxable accounts altogether, since contribution limits and access rules also matter. It simply means tax-aware placement deserves a place in your plan. For decisions about your own situation, talk to a qualified tax or financial advisor, because rules and your personal circumstances change over time.
5. Funnel Payouts Into a Broad Index Position on a Set Schedule
Some investors prefer not to add to the same holding that paid the dividend. Instead, they collect payouts as cash and, on a set schedule, use them to add to a broad, diversified position. This keeps reinvestment automatic in spirit while avoiding concentration in a single company or sector, and it gives you a regular moment to review where your money is going.
The schedule is the key: monthly or quarterly works well for most beginners, because it is frequent enough to keep cash from piling up but calm enough to avoid constant tinkering. Set a reminder, follow the same rule each time, and resist the urge to chase whatever performed best last month.
6. Coordinate Reinvestment Across Brokerage and Retirement Accounts
Many people hold investments in more than one account, and reinvestment settings do not always match across them. One account might reinvest automatically while another lets payouts accumulate as cash, which can leave you with a lopsided portfolio and a surprising cash balance. A short annual check of every account brings those settings back into line.
Think of your accounts as one portfolio rather than separate piles. Decide which account should reinvest which holding, note it in your plan, and check that each brokerage actually followed your instructions. This small coordination step prevents duplicate holdings from growing unevenly and keeps your overall mix closer to what you intended.
Avoid common errors — read these passive income mistakes to avoid.
7. Pause Reinvestment Temporarily for a Planned Cash Goal
There are seasons when cash is more useful than more shares. You might be saving for a home repair, building a short-term reserve, or covering a planned expense without selling investments. Pausing reinvestment for a defined period lets dividends flow to cash for that goal, then resume compounding once the goal is met.
Make the pause deliberate, with a start date, an end date, and a clear purpose. An open-ended pause tends to become permanent, and months of missed reinvestment are hard to notice until you review your statements. Put a reminder on your calendar to switch the setting back on when the goal is complete.
8. Review and Redirect Dividends After a Payout Cut
A dividend cut is useful information, not just a disappointment. It can signal that a company is under pressure, changing strategy, or preserving cash, and it is a good prompt to review whether that holding still fits your plan. Rather than reinvesting on autopilot, take time to understand what changed and whether you want future payouts to keep going into the same place.
You do not need to sell immediately, and a single cut does not automatically make a holding a bad one. The smarter move is to pause, read the company’s explanation, and decide consciously: keep reinvesting, redirect payouts elsewhere, or reduce the position. A deliberate decision beats a panicked one every time.
9. Keep a Simple Annual Log of Reinvested Shares
Reinvestment is easy to forget precisely because it happens automatically. A simple annual log — the holdings you reinvested in, roughly how many shares were added, and any settings you changed — gives you a record you can actually review. It also helps at tax time, since reinvested dividends can affect your cost basis in a taxable account.
Your brokerage statements already contain the details, so this log does not need to be elaborate. Once a year, note the key figures in one place and check them against your plan.
10. Put Small Payouts to Work Instead of Leaving Them Idle
Small payouts feel too tiny to matter, but they are exactly the payouts most likely to be ignored. A few dollars sitting as cash in a brokerage account earns nothing toward your goals and is easy to overlook for months. Fractional-share reinvestment, where available, solves this by letting even a small payout buy a slice of a share.
If your brokerage does not offer fractional reinvestment for a holding, collect small payouts and sweep them into your scheduled purchase instead. The point is to give every payout a job, however small. Over many years, it is the steady accumulation of small amounts that builds a noticeably larger position.
11. Audit Your Reinvestment Settings at a Yearly Check-In
Brokerages update platforms, accounts get transferred, and holdings change, so settings that were correct last year may not be correct today. A yearly check-in catches those drifts: confirm each holding’s reinvestment setting, verify that new positions were set the way you intended, and update your written plan to match reality.
Use the same check-in to ask whether your strategy still fits your life. Income needs, tax situations, and goals all shift over time, and your plan should shift with them.
Frequently Asked Questions
Do reinvested dividends still count as taxable income?
In a taxable brokerage account, dividends are generally taxable in the year you receive them even if you reinvest them, while retirement accounts have different rules. Keep your statements and ask a qualified tax advisor about your own situation.
Is automatic reinvestment better than taking dividends as cash?
Neither is universally better. Automatic reinvestment supports compounding and requires less attention, while cash payouts give you flexibility for spending or rebalancing. The right choice depends on your goals, income needs, and tax situation.
Can small dividend payouts really make a difference?
Yes, over a long period. Small payouts that buy additional shares can themselves generate future payouts, and that compounding effect grows with time. The key is consistency rather than the size of any single payment.
Should I reinvest dividends from every holding I own?
Not necessarily. Some holdings may already be larger than you want, or you may prefer to redirect their payouts to underweight positions. Review your overall mix and set each holding’s reinvestment choice deliberately.
How often should I review my reinvestment plan?
Once a year is a good rhythm for most beginners, plus a review after a major life change or a dividend cut. Frequent changes usually add noise without adding results, so keep reviews scheduled and calm.